OOH Is Booming. So Why Does Innovation Still Take So Long to Scale?
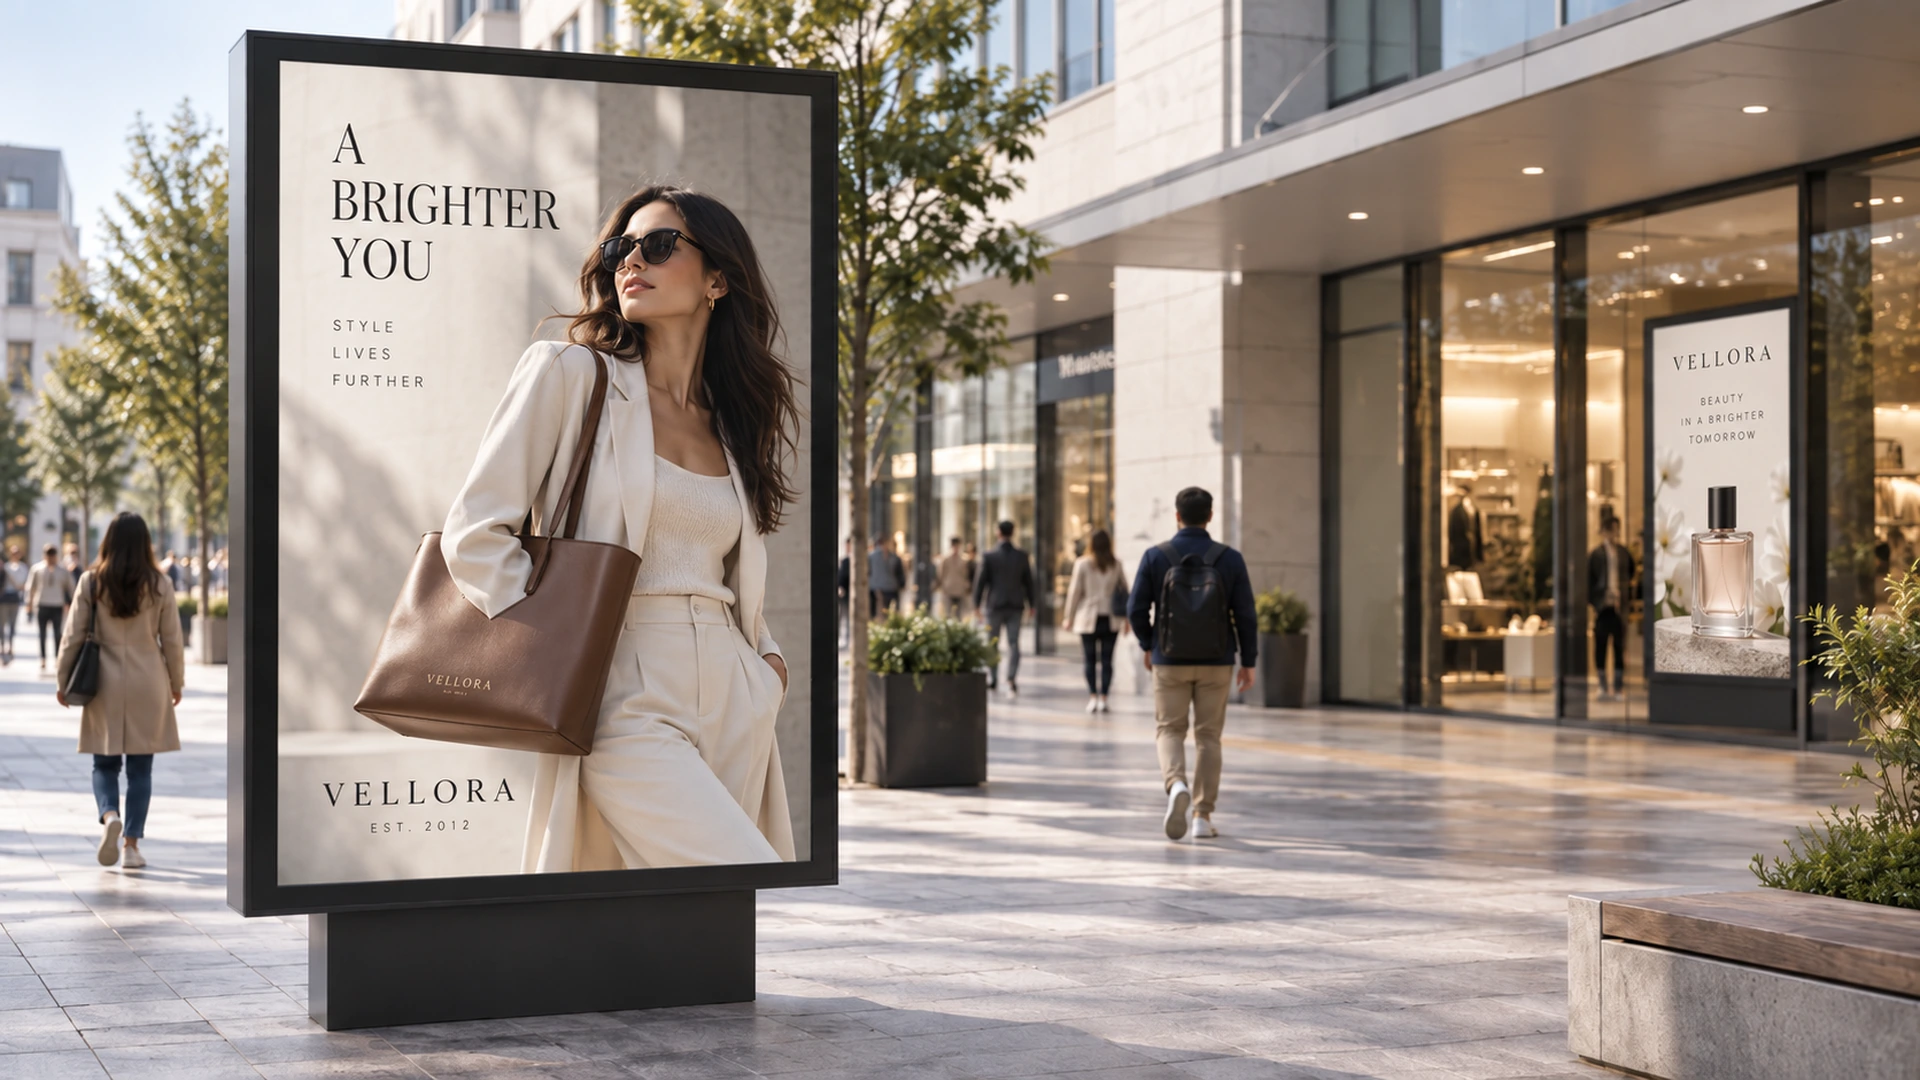
Out of Home advertising is growing fast, but the journey from new technology to mainstream media format can still take years.
Out of Home advertising is in remarkably good health. Global OOH expenditure reached $54.2 billion in 2025, an increase of 15% on the previous year, according to the World Out of Home Organization. Digital Out of Home accounted for $25.5 billion, or 47% of all OOH revenue, and WOO forecasts that digital will reach 49% in 2026, putting it on the verge of overtaking static OOH for the first time.
Those numbers tell the story of an industry that has successfully reinvented a large part of itself. Posters became screens, fixed campaigns became dynamic, and individual locations became connected networks. Advertisers can change creative remotely, use data to determine when content appears, and increasingly buy inventory through digital platforms. Yet another statistic reveals a very different side of the story.
In June 2026, WOO published what it described as the first independently aggregated global study of programmatic Digital Out of Home expenditure. Eleven major Supply-Side Platforms submitted their data confidentially to PwC, producing a global estimate of approximately $1.4 billion of programmatic DOOH expenditure in 2025. That represented just 7% of total Digital Out of Home expenditure. The technology exists, the screens are connected, the platforms are established, and advertisers understand automated media buying. Yet widespread adoption still takes time. Perhaps that tells us something important about the next generation of Out of Home advertising too.
OOH does innovate, but adoption can be painfully slow
It would be wrong to describe Out of Home as an industry that does not innovate. Some of the world's most technically ambitious advertising installations are OOH campaigns. Huge digital spectaculars, anamorphic 3D creative, dynamic content, audience measurement, mobile integration, computer vision, interactive installations and programmatic buying all demonstrate how sophisticated the industry has become.
The real issue is that invention and widespread adoption are very different things. The internet can introduce a new advertising format through software and potentially make it available to millions of users almost immediately. Physical media does not work that way. Every meaningful change to OOH can involve property owners, planning regulations, media owners, manufacturers, electrical infrastructure, installation, maintenance, content production, measurement companies, agencies, sales teams and advertisers. New technology has to survive not only a technical test, but a commercial and operational one.
That naturally creates friction. The programmatic numbers illustrate just how significant that friction can be. WOO's independently aggregated data found programmatic penetration at 14.2% of DOOH expenditure in the Americas and 9.4% across EMEA, but only 1.7% across APAC, despite APAC being the world's largest DOOH market by overall expenditure. These regions have access to much of the same underlying technology. What differs is the ecosystem surrounding it, including media buying practices, market structure, integrations, measurement and the willingness of participants to change established processes.
That distinction is important when considering technologies such as holographic advertising. The question is not simply whether holographic displays work. They already do. The more interesting question is how long it takes an established industry to turn a new medium from something unusual into something routinely purchased.
Digital transformed the billboard, but it did not fundamentally change the screen
The transition from printed posters to Digital Out of Home was enormous. A single location could suddenly display multiple advertisers. Creative could be changed without sending somebody to replace a poster. Video became possible, campaigns could respond to time, weather, traffic and other data, networks could be managed remotely, and inventory could eventually be offered through automated buying platforms.
But there is an interesting contradiction at the centre of this transformation. The intelligence behind the screen has changed dramatically, while the physical relationship between the audience and the advertising surface has changed much less. A poster became a digital poster. A billboard became a digital billboard. A six-sheet advertising panel became a digital six-sheet advertising panel. A shopping centre screen became a higher-resolution shopping centre screen.
The technology improved enormously, but in most cases the fundamental object remained a flat rectangular surface displaying content. There is nothing inherently wrong with that. Conventional screens are efficient, scalable, reliable and appropriate for an enormous number of advertising environments, and they will continue to be a major part of OOH.
The challenge is that endlessly improving screen resolution, brightness and size eventually produces diminishing differences from the audience's perspective. An 8K advertising screen is technically superior to a 4K screen, but somebody walking through a shopping centre may not experience it as an entirely new medium. That matters because the environment around OOH has changed so dramatically.
Consumers now walk through cities carrying some of the most sophisticated media devices ever created. Their phones contain TikTok, Instagram, YouTube, streaming services, games, messaging and increasingly artificial intelligence. Every one of those platforms is competing continuously for their attention. Physical advertising therefore cannot rely indefinitely on simply becoming a slightly better version of the screen that came before it. At some point, innovation needs to change the experience itself.
The next evolution of OOH could move beyond the flat screen
This is where technologies such as holographic displays become interesting. Holographic media does not have to replace Digital Out of Home. That would be neither realistic nor desirable. OOH has always consisted of different formats serving different purposes, from giant roadside billboards and transport advertising to street furniture, retail media and landmark digital spectaculars.
Holographic displays can become another format within that ecosystem, particularly in premium locations where attention, interaction and experience matter. Instead of showing a person on a conventional portrait screen, a brand can present a full-body digital human with apparent physical presence and depth. A product can appear three dimensional. A character can occupy physical space. An AI-powered brand ambassador can respond to a person standing in front of it. An advertising installation can become something audiences approach, photograph, interact with and remember.
That distinction matters because one of the greatest challenges facing advertising is not simply reach. It is attention. OOH already possesses something most other modern media channels cannot replicate: physical presence in the real world. The next opportunity may be to make far greater use of that advantage.
At Miirage, this is how we view holographic display technology. It is not simply another way of playing a video. The objective is to change the audience's perception of what is physically occupying the space in front of them. When combined with AI, that distinction becomes even more significant. The display stops being only an advertising surface and starts becoming an interface.
A digital person can potentially welcome somebody, answer questions, provide directions, explain a product, deliver training, communicate in different languages or connect an audience to a brand in real time. That begins to blur the boundaries between OOH, retail media, digital signage, experiential marketing and conversational AI. It is also precisely why fitting technologies like this into existing media categories can take time.
The most innovative markets may not necessarily be the oldest ones
There is another interesting development taking place geographically. Some of the markets moving most aggressively into new forms of physical media are not necessarily those with the longest history of established OOH infrastructure.
The Gulf is a particularly interesting example. In 2025, WOO President Tom Goddard highlighted the exceptionally strong position of OOH across the GCC, reporting that the medium represented around 20% of regional advertising expenditure, while Digital Out of Home was heading towards approximately 70% of the OOH market. The regional OOH market was expected to grow from $1.5 billion to $1.8 billion.
That level of digital penetration is significant. Saudi Arabia and the wider Gulf are also undergoing enormous investment in new malls, airports, entertainment destinations, tourism developments and urban infrastructure. New physical spaces offer something that mature markets do not always have: the opportunity to design media environments around today's technology rather than retrofit new technology into environments designed decades ago.
That potentially allows markets to leapfrog. Instead of asking how an emerging medium fits into an existing network of conventional displays, developers can ask a much more interesting question: if we were designing the customer experience today, what should actually be there? The answer might include conventional DOOH screens. It might also include interactive installations, AI assistants, holographic brand ambassadors and digital humans. The important point is that the physical media environment does not have to remain frozen in the form it inherited from the past.
OOH is growing strongly enough to take bigger risks
The most exciting thing about this discussion is that OOH does not need innovation because the industry is failing. It needs innovation precisely because the industry is succeeding.
The United States illustrates that strength. OOH advertising revenue reached a record $9.46 billion in 2025, marking 19 consecutive quarters of growth. Digital OOH increased 10.5% during the year. In the second quarter of 2026, US OOH revenue then jumped another 10.7% year on year to $3.16 billion, the first time quarterly revenue had passed $3 billion. Digital OOH grew 18.5% during that quarter, according to the Out of Home Advertising Association of America.
Globally, WOO's $54.2 billion figure tells a similar story. This is not a declining legacy medium desperately searching for relevance. It is a growing global advertising channel with something increasingly valuable in an overwhelmingly digital world: access to real physical space and real human audiences.
But success can create its own form of inertia. If conventional formats continue generating revenue, there is naturally less urgency to replace them. Media owners know how to sell them, agencies understand how to buy them, measurement systems understand how to evaluate them, and content workflows already exist. New formats disrupt that comfortable structure.
Initially, they may require different creative. Sales teams have to explain them. Advertisers need to understand them. Pricing models need to develop. Measurement needs to evolve. Locations need to prove demand. Programmatic DOOH demonstrates how long that process can take, even when the destination appears obvious.
For emerging physical media, the same thing could happen again. Holographic advertising may spend several years being treated as an unusual experiential format before the market begins to recognise it as something that can be standardised, networked, remotely managed, measured and commercially packaged in much the same way other OOH inventory is today. Once that happens, adoption can accelerate surprisingly quickly.
The technology may move faster than the industry
There is a pattern that appears repeatedly in technology. At first a new format seems unnecessary. Then it becomes interesting. A handful of companies experiment with it, customers start asking for it, infrastructure develops around it, prices fall and standards emerge. Eventually, something that spent years appearing to go nowhere begins moving very quickly.
Digital Out of Home followed that path. Programmatic DOOH is still travelling along it. Holographic displays and AI-powered physical media may be much earlier on the same curve.
For Miirage, that is the opportunity. We believe the next generation of Out of Home will not simply involve installing more conventional screens in more locations. Screens will remain enormously important, but around them a new category of physical digital experiences is beginning to emerge.
Displays can become interactive, advertising can become conversational, digital humans can occupy physical environments, and AI can move beyond phones and laptops and into airports, malls, retail stores, events and public spaces. The most powerful characteristic of OOH has always been extraordinarily simple: it exists in the real world.
As almost every other area of media becomes increasingly virtual, personalised and confined to individual screens, that physical presence may become more valuable rather than less. The opportunity for OOH is therefore not to become more like online advertising. It is to use technology to become much better at being something online advertising can never truly become: part of the physical world around us.
The technology is moving quickly, and audience expectations are moving quickly with it. The question is whether the industry will move quickly enough too.
OOH already owns physical space. The next opportunity is to make that space far more intelligent, interactive and memorable.Further Reading
- World Out of Home Organization: Global Out of Home Expenditure Report 2026
- World Out of Home Organization: Global pDOOH Market
- World Out of Home Organization and PwC: Global pDOOH Expenditure Study 2025
- World Out of Home Organization: GCC OOH Industry and Digital Penetration
- OAAA: OOH Revenue Surges to $3.16 Billion in Q2 2026